Education & Planning
Homebuyer Resources - Mylo Mortgage | Denzil Alton Davis - Broker
Homebuyer Resources — Education, Tools, and Guidance for Confident Homeownership
Homebuyer Resources
Buying a home is a major step. Mylo Mortgage provides the resources you need to move forward informed and prepared. The Homebuyer Resources page collects practical guides, checklists, calculators, and planning tools to help first-time and repeat buyers alike. Below you’ll find why these resources matter, key benefits of using them, how Mylo Mortgage supports your journey, frequently asked questions, and how to reach out for personalized assistance.
Why homebuyer resources matter
A successful home purchase depends on more than a good credit score or attractive house; it requires planning, documentation, and realistic expectations. Resources help you:
Understand loan products and associated costs.
Prepare documentation to streamline approval.
Budget for down payment, closing costs, and ongoing homeownership expenses.
Avoid common pitfalls that delay closing or jeopardize approval.
Key resources included
Step-by-step buying timeline
We provide a clear timeline breakdown from pre-approval to closing with typical milestone durations:
Pre-approval: 1–3 business days depending on documentation
Home search and offer acceptance: variable, often 2–8 weeks
Underwriting and appraisal: 5–15 days, depending on the program.
Closing: Typically 25–35 days. At Mylo, we’re built to move faster when needed.
This timeline helps you coordinate inspections, escrow deposits, and move dates.
This timeline helps you coordinate inspections, escrow deposits, and move dates.
Document checklist
Preparing documents early shortens processing times. Our checklist includes:
Government ID (driver’s license)
Social Security number
Two years of W-2s or 1099s and tax returns
Recent pay stubs covering 30 days
Two months of bank statements for all accounts
Documentation of assets (retirement accounts or stocks)
If applicable: bankruptcy discharge papers, divorce decrees, or rental history
Budgeting and affordability worksheets
Use our budgeting tools to evaluate:
Target monthly mortgage payment (including taxes and insurance)
Closing costs and reserves
Home maintenance and utilities estimates
Emergency fund planning
This timeline helps you coordinate inspections, escrow deposits, and move dates.
Mortgage calculator
We provide calculators and examples for:
Monthly payment estimates (principal, interest, taxes, insurance)
Affordability based on income and debts
Refinance savings and break-even analysis
How additional principal payments accelerate equity
Review the reference page to determine the appropriate calculator functionality and layout. If the calculator cannot be embedded directly, identify a suitable alternative that provides similar functionality and a consistent user experience.
This timeline helps you coordinate inspections, escrow deposits, and move dates.
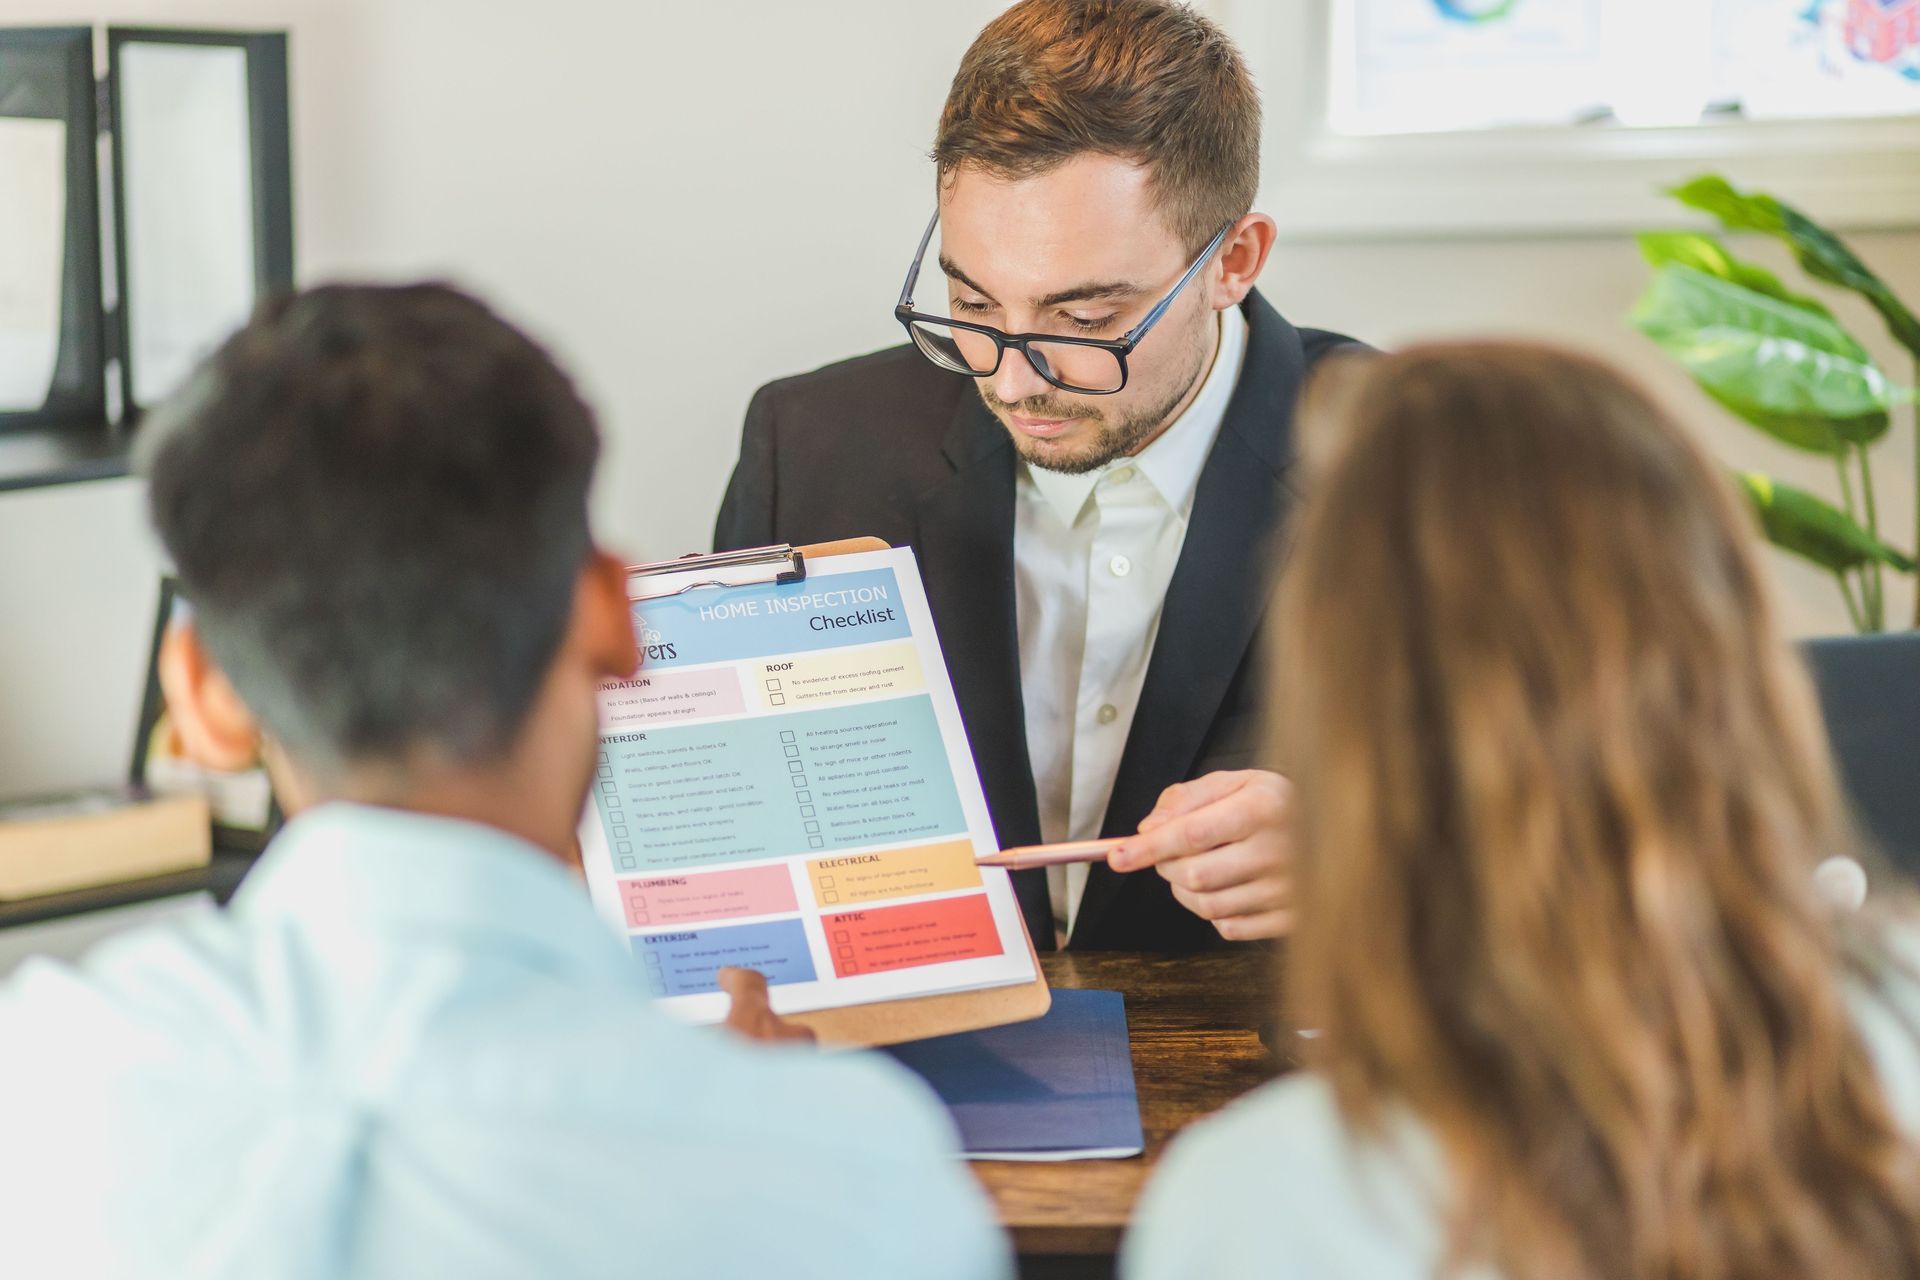
Home inspection and appraisal guidance
We explain what to expect during inspection and appraisal, how appraisers determine value, and how to address appraisal gaps in negotiations.
Credit and loan qualification guidance
Understand how credit scores, debt-to-income ratios, and employment history affect loan programs. We provide strategies to improve credit, manage collections, and document non-traditional income sources.
This timeline helps you coordinate inspections, escrow deposits, and move dates.
FHA and VA-specific guides
We provide detailed explanations of FHA mortgage insurance premiums, loan limits, VA Certificate of Eligibility (COE) requirements, and the VA appraisal process.
Credit and loan qualification guidance
This timeline helps you coordinate inspections, escrow deposits, and move dates.
Understand how credit scores, debt-to-income ratios, and employment history affect loan programs. We provide strategies to improve credit, manage collections, and document non-traditional income sources.
Down payment and assistance information
We explain common down payment sources:
Personal savings
Gift funds (with documentation)
Down payment assistance programs and eligibility criteria
We also provide guidance on when seller concessions may be appropriate.
How Mylo Mortgage supports your use of these resources
Personalized walkthrough
We review your completed pre-approval documents and resource worksheets to ensure you’ve addressed potential underwriting issues.
Action plan
Based on your profile, we create a checklist prioritized by impact to your approval and timeline.
Proactive communication
We notify you of missing documents and follow up with clear instructions so processing is not delayed.
Educational calls
Schedule an appointment to review mortgage basics, the home purchase timeline, or refinance scenarios.
Contact
Mylo Mortgage Denzil Alton Davis - Broker
Address: 105 Hunters Ln Suite 106, Friendswood, TX 77546
Phone: (832) 372-5570
FAQs specific to loan selection
What’s the difference between pre-qualification and pre-approval?
Pre-qualification is an initial estimate based on self-reported information. Pre-approval is a conditional commitment after documentation review and is stronger when making offers.
How much should I save for closing costs?
Closing costs typically range from 2% to 5% of the home purchase price depending on loan type and local fees. We provide a precise estimate for your target loan program.
Can I use retirement funds for a down payment?
Yes, with certain rules and tax considerations. We recommend consulting your financial advisor and reviewing plan rules for early withdrawal or loan options.
How do I read my mortgage estimate?
We walk you through the Loan Estimate form, explaining interest rate, APR, monthly principal and interest, estimated taxes/insurance, and closing cost breakdowns.
How do I handle a low appraisal?
Options include negotiating with the seller, ordering a reconsideration of value with additional comps, bringing additional cash to closing, or cancelling if your contract permits.